$0 Down Provider Program
· North Houston
Your income says yes. Your student loans say no.
You earn a strong income, and a conventional lender still counts a full student loan payment against you, still wants a down payment you have not had time to save, and still wants pay stubs from a job that starts in six weeks.
A lender I work with offers the $0 Down Provider Program, and it addresses each of those: 100% financing, no mortgage insurance, student loan payment flexibility when qualifying, and employment contracts accepted.
No credit pull to start. A 10-minute call tells you if this fits.
0% Down payment on the 100% financing tier
Program snapshot
$0 Down Provider Program
Down payment
0% — 100% financing
Mortgage insurance
None
Student loan debt
Flexible treatment
Income documentation
Employment contract OK
Minimum middle score
700
Occupancy
Primary residence only
Subject to lender qualifications and terms. Closing costs, prepaids, and escrow still apply. Not a commitment to lend. Equal Housing Opportunity.
Eligible degrees:
MD
DO
DDS
DMD
Ophthalmology (MD/DO)
Psychiatry (MD/DO)
PharmD
VMD
DPM
CRNA (DNAP/DNP)
NP (MSN/DNP)
Residents, fellows & interns
Three walls the program removes,
and the 4th that I handle for you
Most mortgages are set up for a buyer with years of pay stubs and no student debt. That is not where a resident, fellow, or new attending is. Here is what usually goes wrong, and what this program does about it.
"Come back when you have the down payment saved." You have been earning a real income for a few years, not a few decades. A conventional loan wants 3% to 20% in cash at closing, and under 20% it adds mortgage insurance every month.
1. So: 100% financing, and no mortgage insurance
No down payment. No PMI line on the statement. Closing costs, prepaids, and escrows still apply; the lender quotes those for your file.

Your debt-to-income comes back wrecked by loans you are barely paying on. A regular lender counts a monthly student loan payment against your income, and on a six-figure balance that one line can push the ratio over the limit even though your salary carries it easily.
2. So: Student loan payment flexibility when qualifying
The lender applies flexible treatment to your student loan payment when qualifying you. How that is calculated on your file is the lender's call; ask it on the first call.

You start at the hospital in six weeks and the lender wants thirty days of pay stubs from a job you have not begun. So you sign a twelve-month lease, move twice, and pay a year of rent on a salary that could have carried a mortgage.
3. So: Employment contracts accepted
Relocating for a hospital or group start date in North Houston? Bring the contract you already signed to the lender call. The lender sets how close to your start date closing has to be, so that is the first question to ask.

You want to see the houses, pick the lot, and read the contract yourself. You just do not have a free Tuesday afternoon to do any of it.
4. So: Your time goes to the decisions
I filter by your commute, budget, and start date before you see anything, then book showings in one block on the evening or weekend you have. You walk the homes, pick the lot, and make the calls. I handle the builder, book the inspections, and everything in between.
Nobody has three weeks to find out they don't qualify
The worst part of most mortgage processes is how long it takes to hear no. So here's transparently what's needed to make the process smooth & swift.
Buying a house shouldn't cost you a day off
You can start this from a call room between cases. Here is the whole thing, in the order it happens.
1. The form, 60 seconds. Designation, practice status, credit band. I send the one-page qualifying sheet the same business day.
2. The lender call. I email the introduction by the next business day. The lender reviews your designation, contract, credit, income, and student loans and tells you whether the program fits your file. You are free to use any lender.
3. Me, about 20 minutes. Your commute, price range, new build or resale, and your timeline against your start date. You leave with a search plan and the first homes to see, on video if you cannot get away.
Who you are working with: Dr. D.J. Onuaguluchi, PharmD and REALTOR® with eXp Realty. I know what a clinic day looks like and why "call me back at 2" does not work. My job is the home search and the negotiation; the loan is between you and the lender, and I stay in the loop so nothing stalls while you are on shift. 936-274-7475.
You shouldn't have to explain your own career to your agent
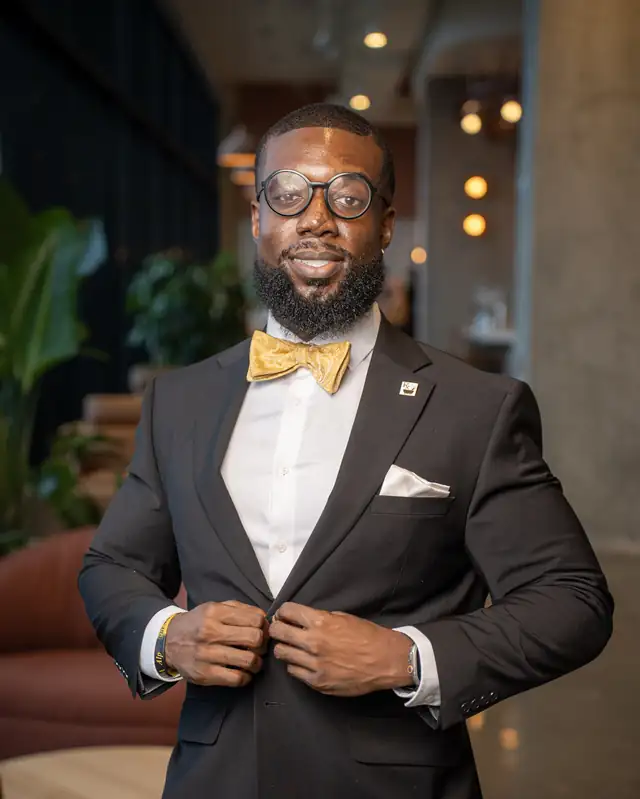
Most agents hear "fellowship" and "credentialing" and nod politely. I'm Dr. D.J. Onuaguluchi — a licensed Texas realtor with eXp Realty and a healthcare professional myself. I already know what a credentialing delay does to a closing date, why your first contract year reads strangely on paper, and what it costs to move a family to a new city three weeks before you start.
My practice is built on creative financing paths for buyers the standard process handles badly. For clinicians, that usually means getting you the strong terms you've already earned — quickly, and without twenty rounds of documentation.
PSA: Pricing Strategy Advisor
CMRS: Certified Military Relocation Specialist
CSMS: Certified Social Media Specialist
Member: Emerald Member, Conroe Chamber of Commerce
Knowledgeable, responsive, and genuinely committed to helping his clients find the right home. His attention to detail made everything feel smooth and stress-free.
Jerrell Horton · Google review
Excellence, professionalism, and integrity define Dr. D.J. Outstanding service, clear communication, and expert guidance from beginning to end.
LaShunda Hinton · Google review
At no point have we felt pressured — only educated, supported, and encouraged to make the best decisions for our family.
Chess Brown · Google review
Featured in Barchart, Times of San Diego, Washington City Paper,
Big News Network, and over 450 news sites.
Questions clinicians actually ask
Do I really put nothing down?
On the 100% financing tier, yes — the program is designed to finance the full purchase price with no mortgage insurance. You'll still need funds for closing costs and any earnest money, though seller or builder credits can often cover part of that. The lender confirms your exact figure at pre-approval.
I'm a resident with $300k in loans. Am I wasting my time?
Probably not. The point of the program is that deferred and income-driven student loan payments get flexible treatment in the debt-to-income calculation, which is precisely the wall residents hit with conventional underwriting. Credit score and occupancy are the real gates, not the loan balance.
I haven't started the job yet. Can I still buy?
Generally yes. A signed employment contract or offer letter with a defined start date can be used in place of pay stubs, which is how relocating clinicians close before their first day. Timing rules vary, so bring me your start date early and we'll build the calendar backward from it.
My middle score is under 700. What now?
The 100% financing option is off the table, but that's one option among several. There are low-down-payment tiers, and my Triple 10 program exists specifically for buyers outside the conventional box. Tell me where your score sits and I'll tell you honestly which door makes sense.
Can I use this for a rental or a second home?
No. This is a primary-residence program only. I'm happy to talk investment strategy separately — it just runs through different financing.
Are you the lender?
No, and that distinction matters. I'm your real estate agent. The loan program, rates, terms, and approval all come from my preferred lending partner, a licensed mortgage professional. I make the introduction, then represent you on the purchase itself. You're free to use any lender you like.
Another lease renewal is another year of someone else's equity
Tell me your start date and your target area.
In ten minutes you'll know whether
this program fits — and if it doesn't,
which one does.